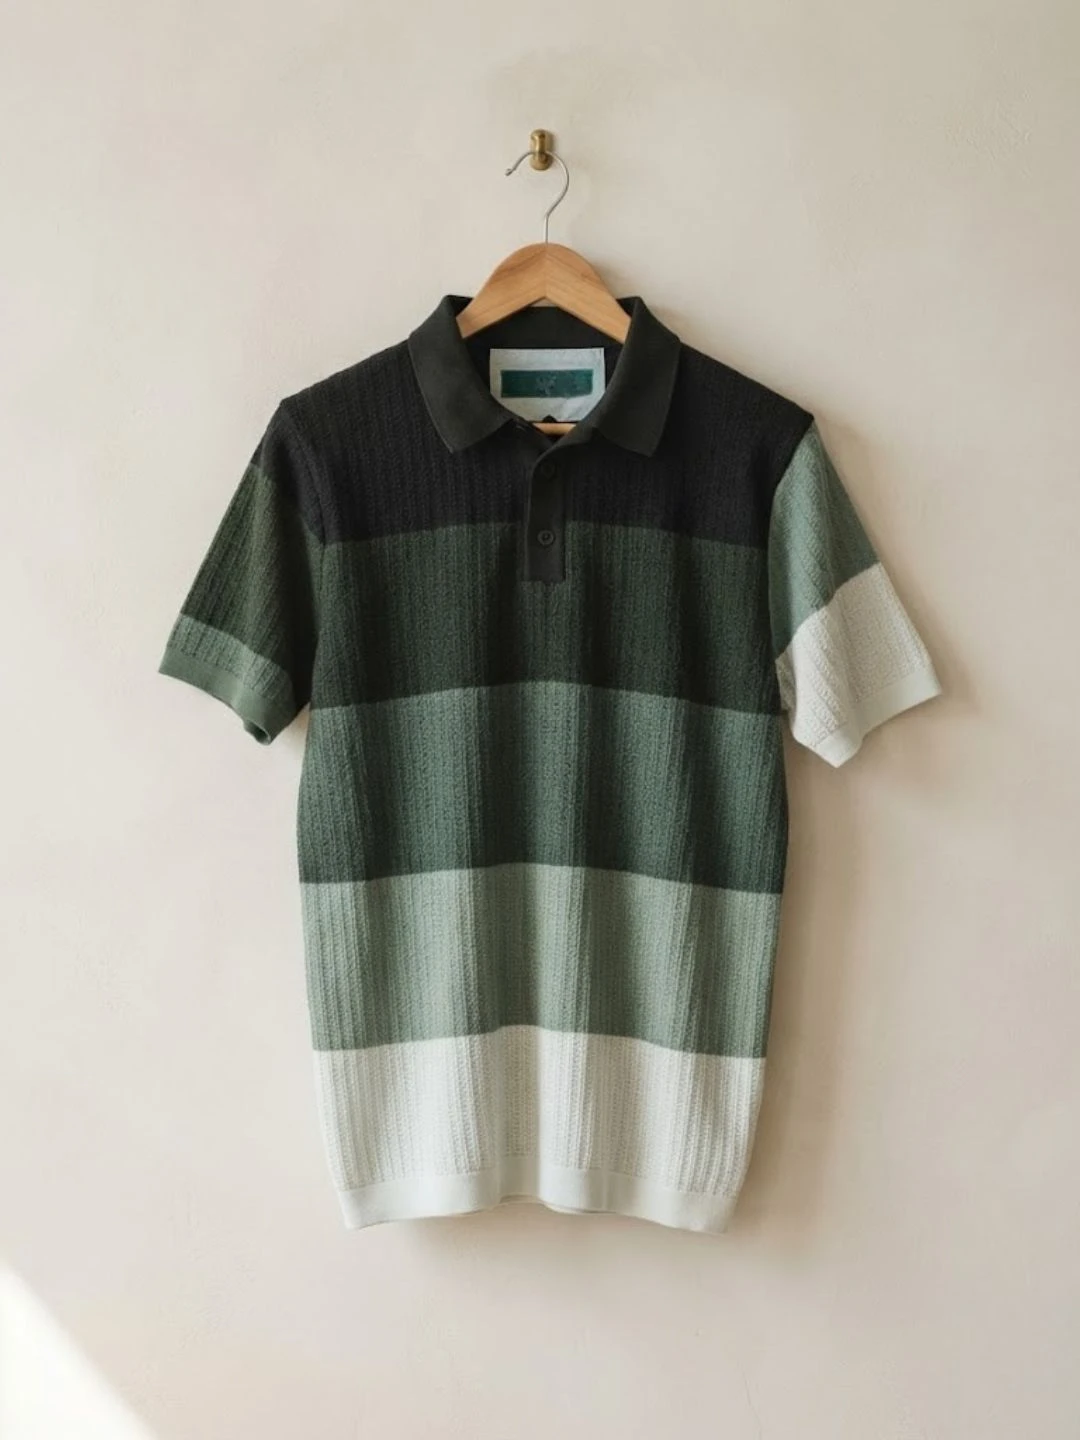
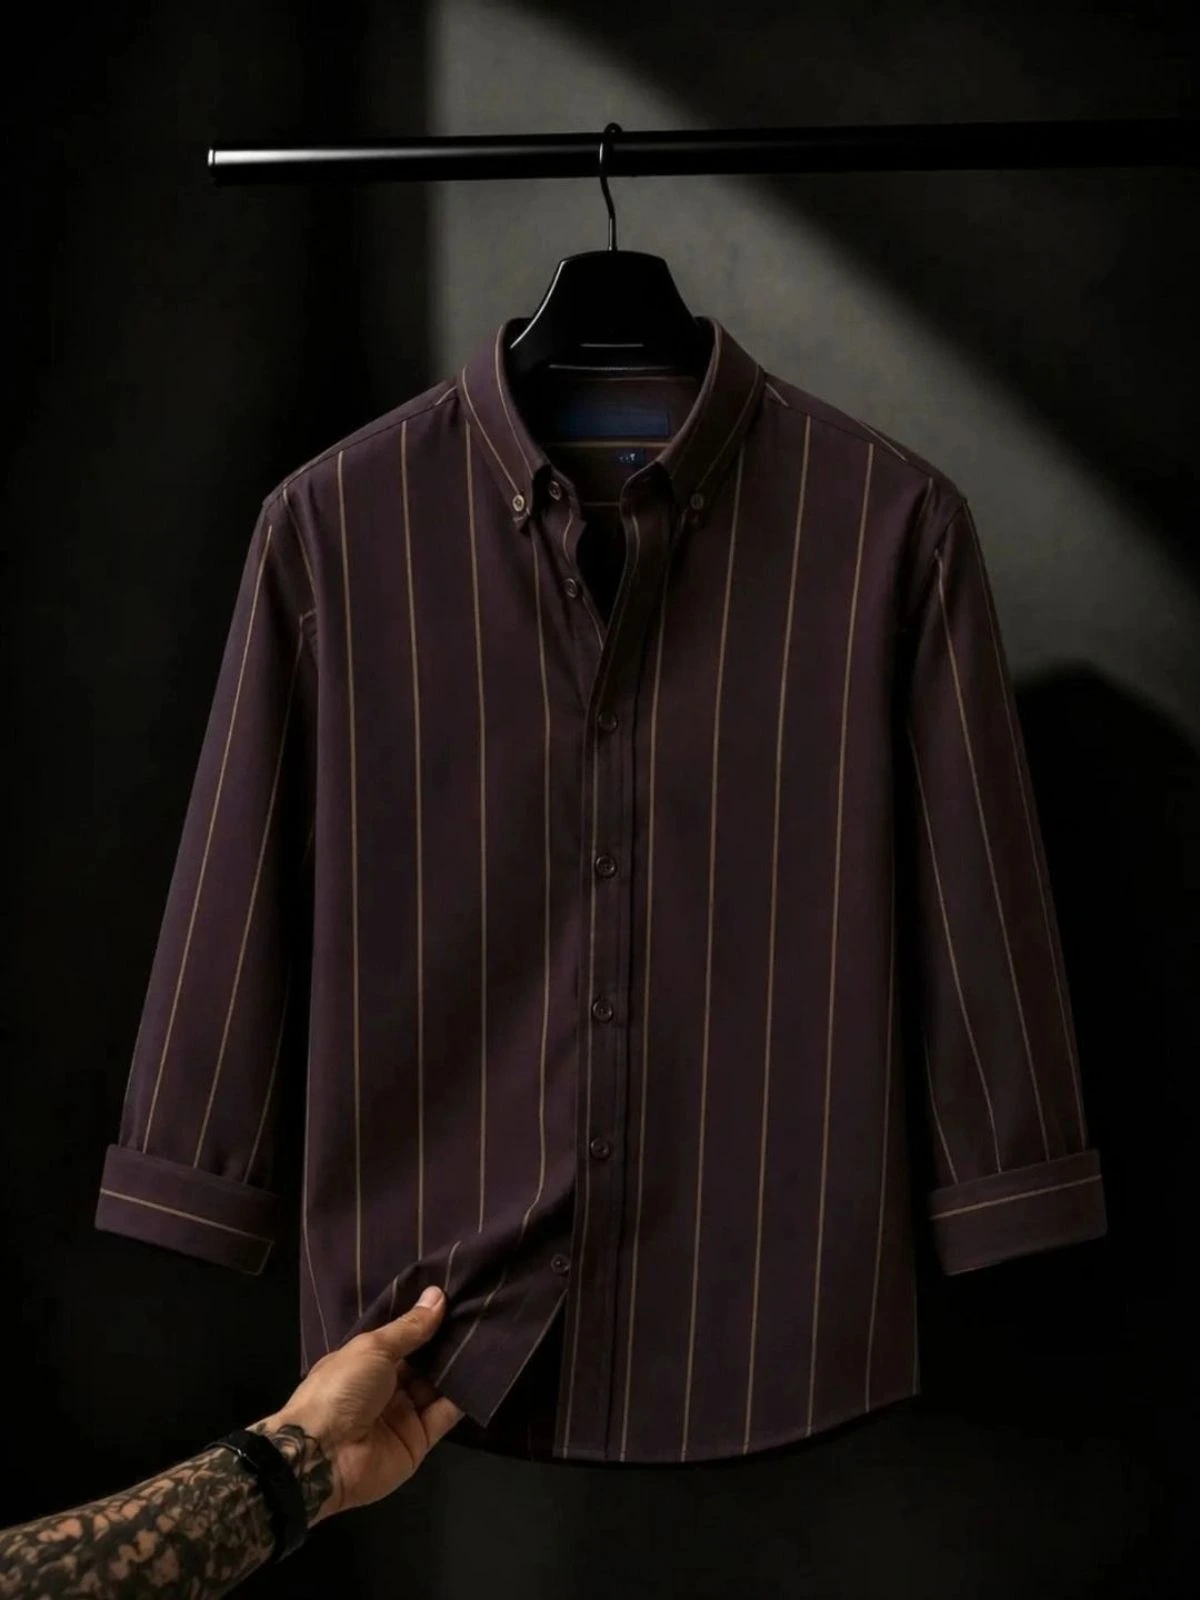
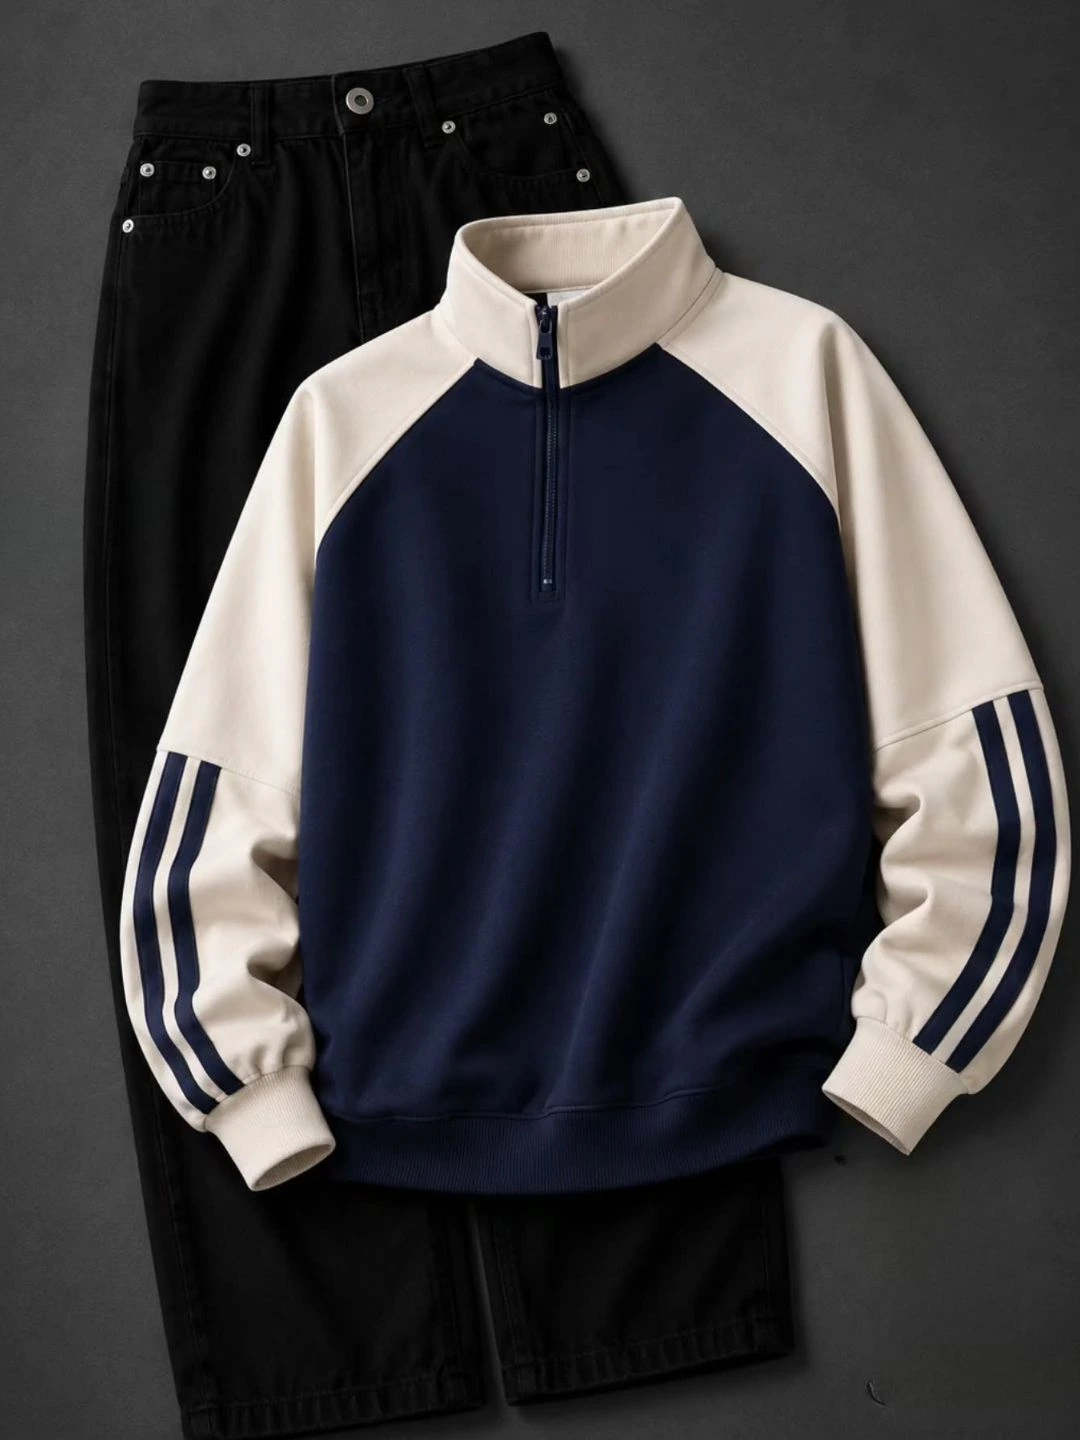
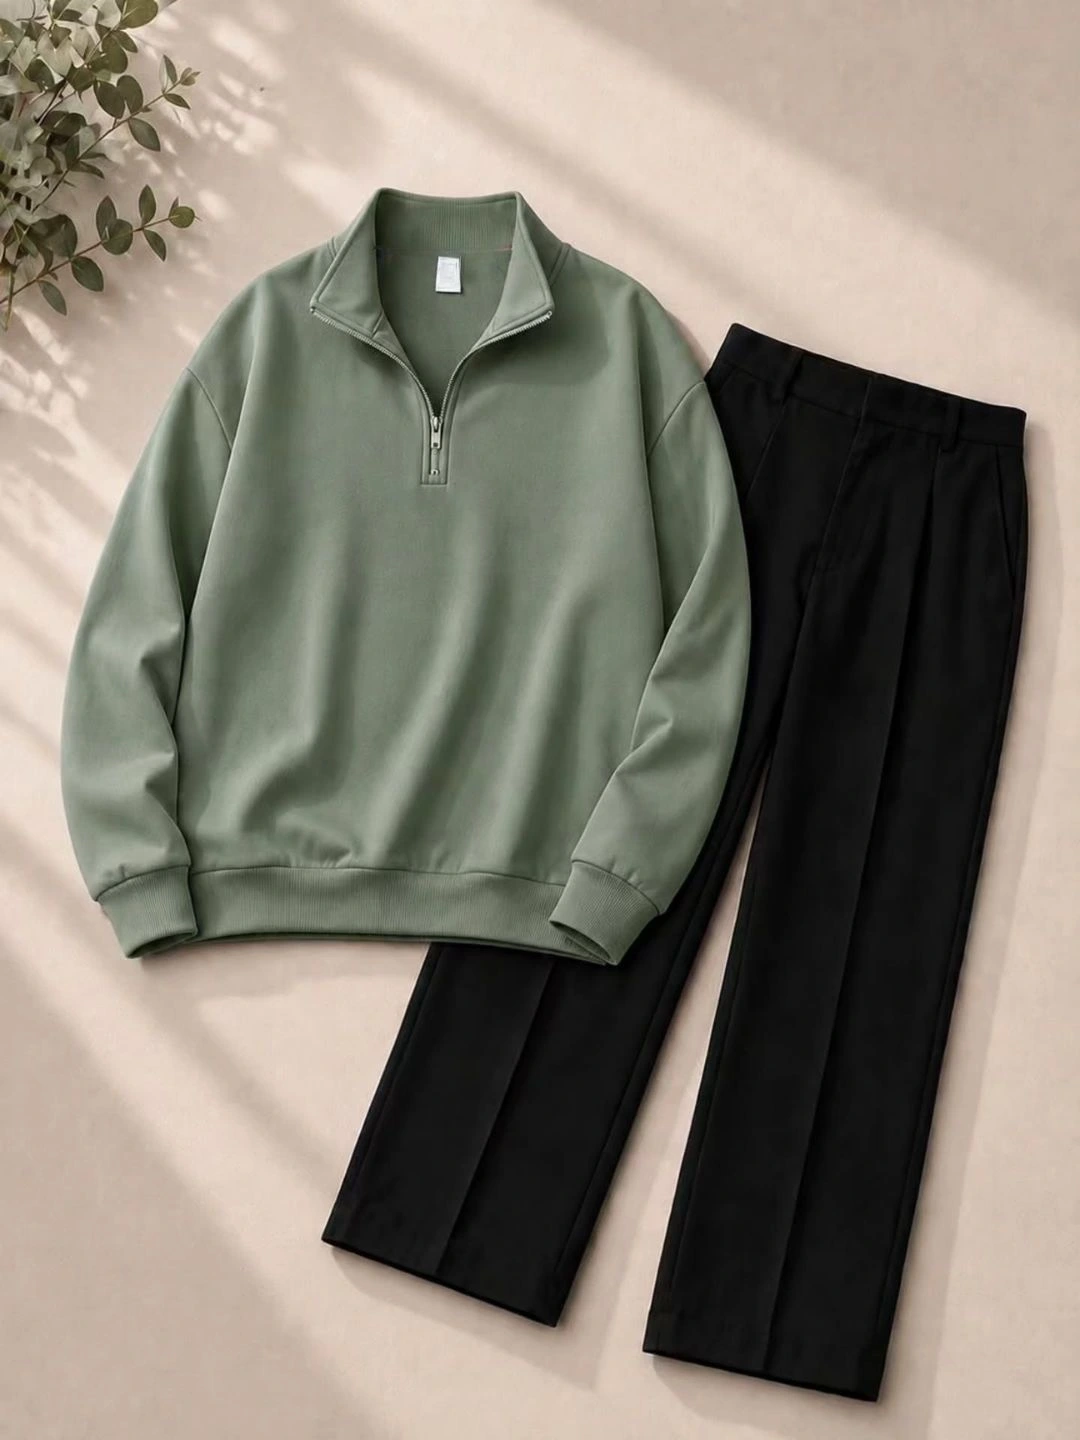
T-shirt & Tailored Trousers Outfit Combo
₹499.00
Sold By
Cotton Culture
3.9
623 Followers
Select Size
Product Description:
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
Product Type: Polo Shirt & Trousers Combo
Sleeves: Short Sleeves
Fit Type: Relaxed Modern Fit
Collar Type: Polo Collar with Half-Zip Placket
Fabric: Premium Textured Knit and Cotton Blend
Pattern: Horizontal Striped Hem Accents with Matching Solid Bottoms
Style: Smart Casual / Contemporary Minimalist / Daily Wear
Occasion: Daily Wear, Casual Outings, Weekend Gatherings, Travel
Upgrade your casual wardrobe rotation with this exceptionally stylish and meticulously coordinated two-piece ensemble, featuring a short-sleeve half-zip polo shirt adorned with striking horizontal striped details along the lower torso and collar trim, paired seamlessly with relaxed matching trousers. Crafted from a soft, breathable, and high-quality fabric blend, this complete outfit guarantees supreme all-day comfort without ever compromising on a sharp, modern silhouette.
The five-year lock-in period that people complain about is honestly a blessing in disguise. It stops you from panic-withdrawing the moment the market dips, which is exactly the kind of discipline most retail investors struggle with when they're managing a regular mutual fund SIP on their own. Add to that the fact that maturity proceeds are usually tax-free under Section 10(10D), and long-term wealth creation through a ULIP starts looking a lot more attractive than people give it credit for.
Where people still go wrong is picking a plan based on the agent's commission incentive rather than their own goals. If you're 25 and saving for retirement thirty years away, an aggressive equity fund option inside your ULIP makes sense. If you're closer to 50, shifting toward debt funds through the free switching option protects what you've already built. Always check the fund switch limit before you sign up, because unlimited free switches give you way more flexibility than a plan that charges you after four or five switches a year.
One thing nobody warns you about enough is the difference between the fund value and the actual amount you'd get on surrender in the early years — surrender charges can eat into your corpus badly if you exit before year five. So treat a ULIP like what it is: a long-term commitment, not a one-year experiment. Compare the fund performance history of at least three insurers before committing, since past fund management quality tends to be a decent indicator of how your money will be handled going forward.