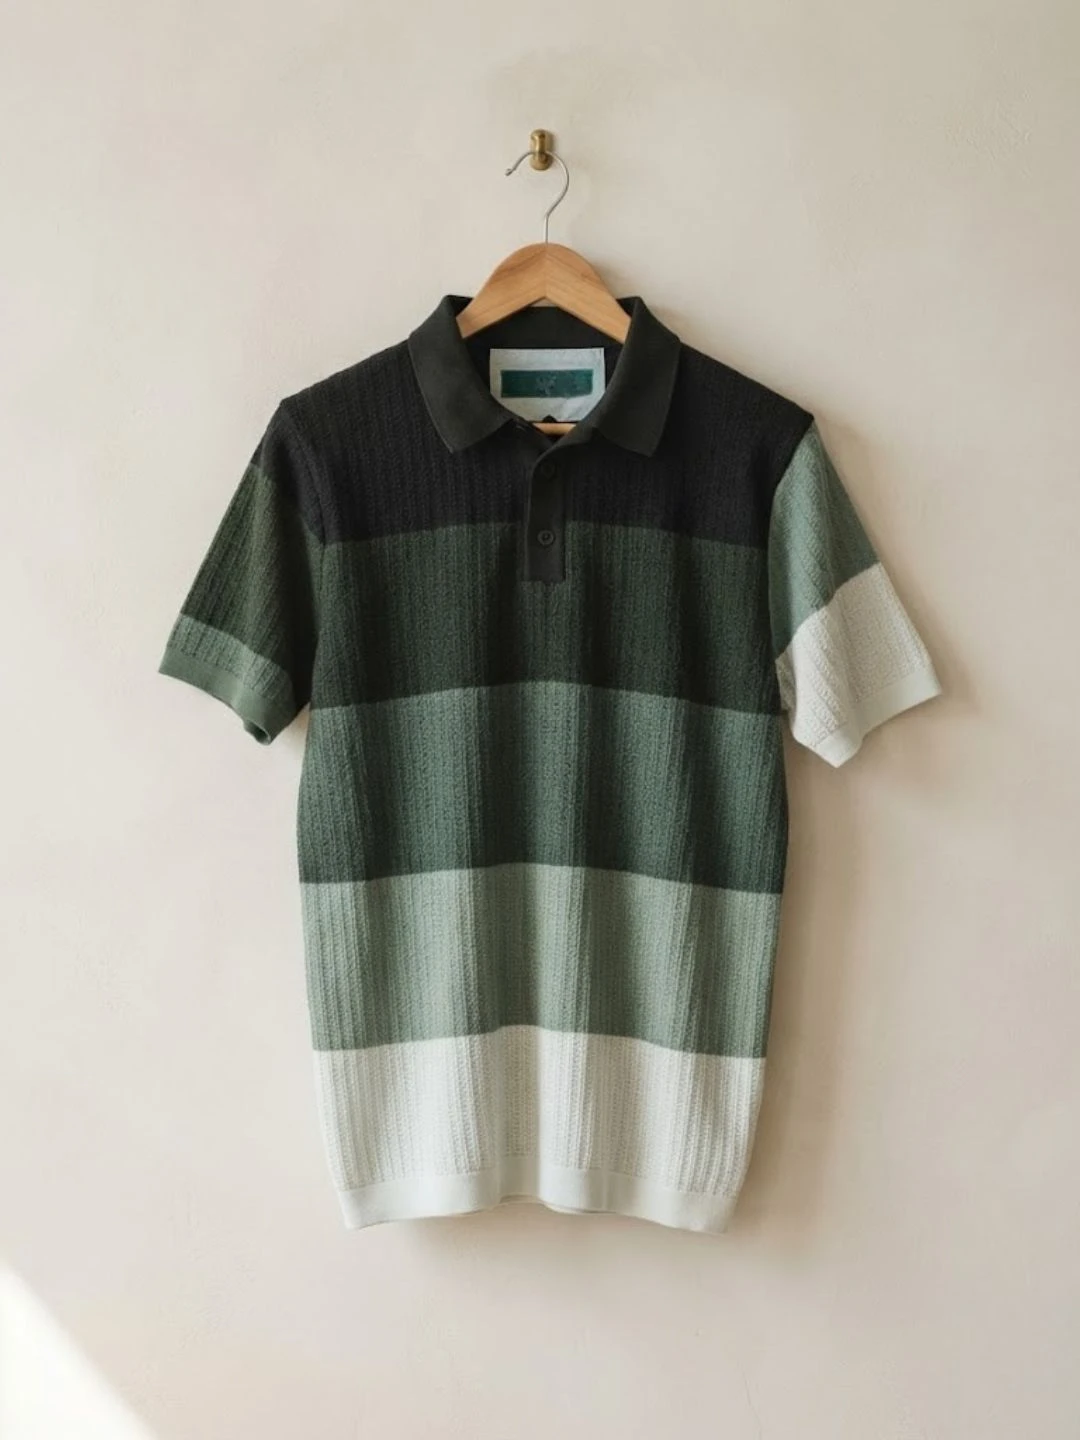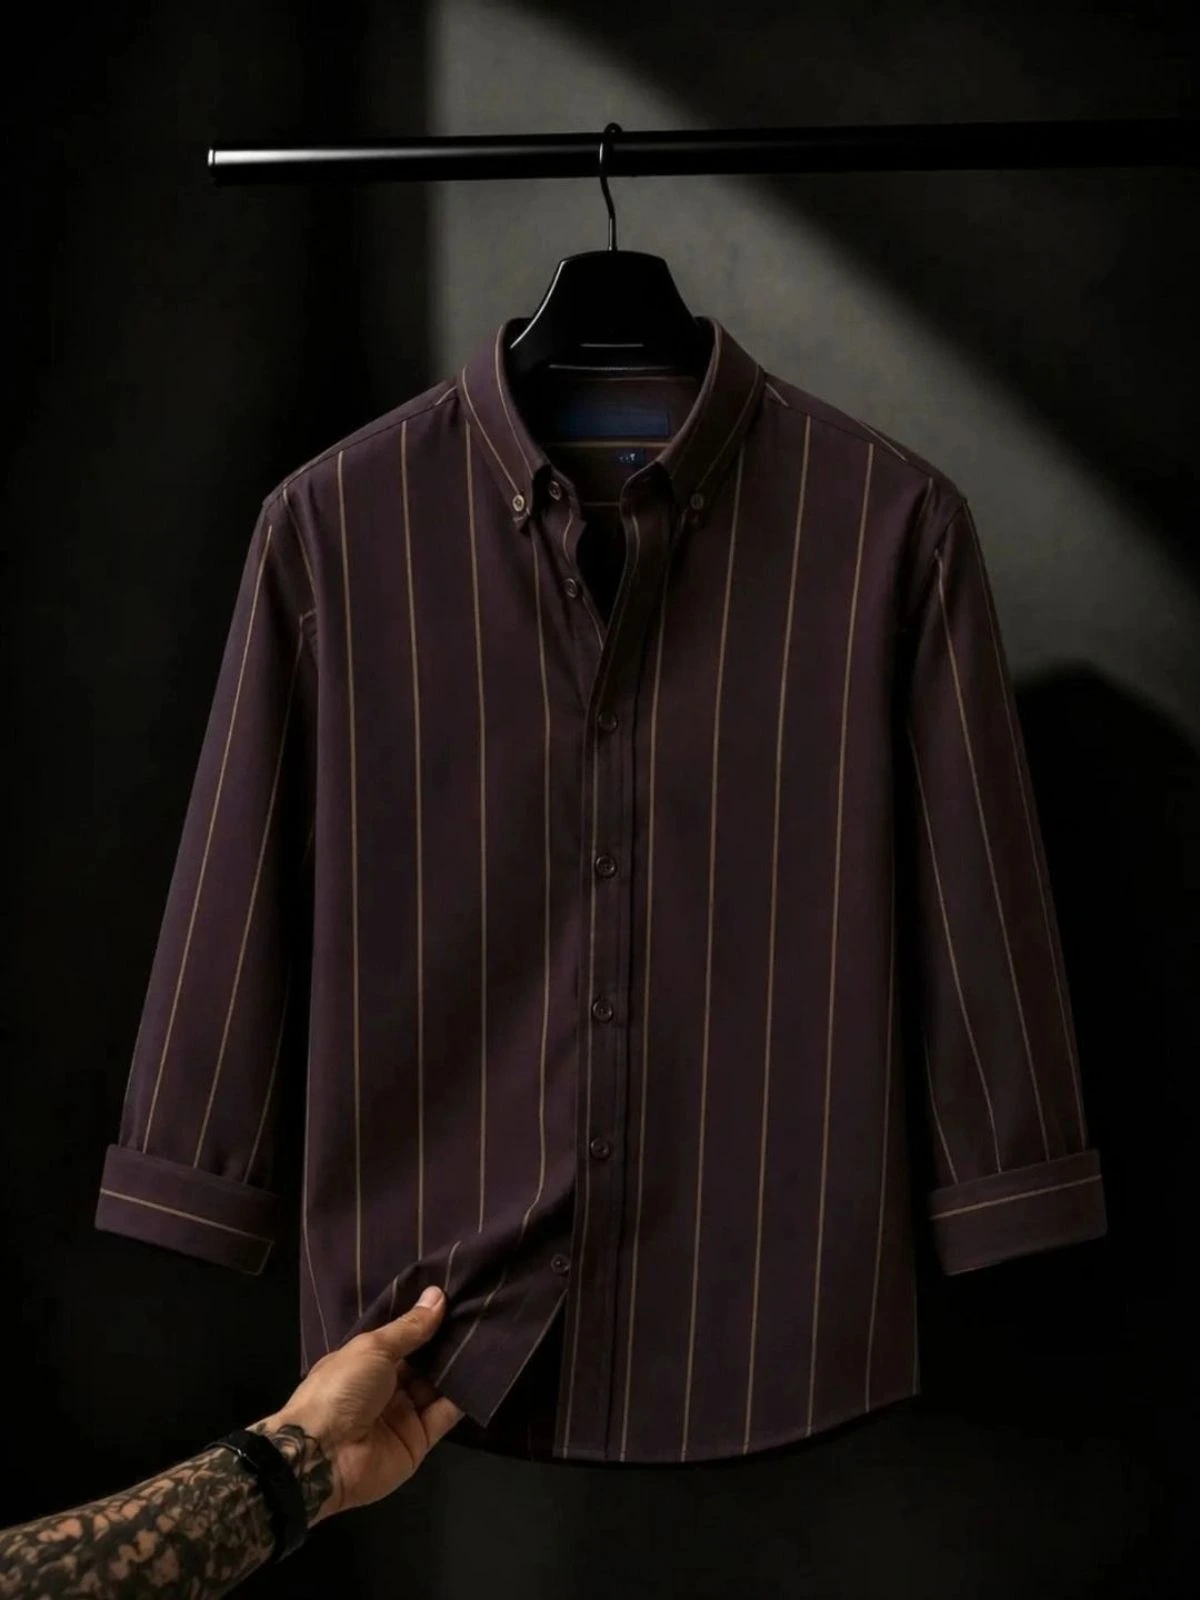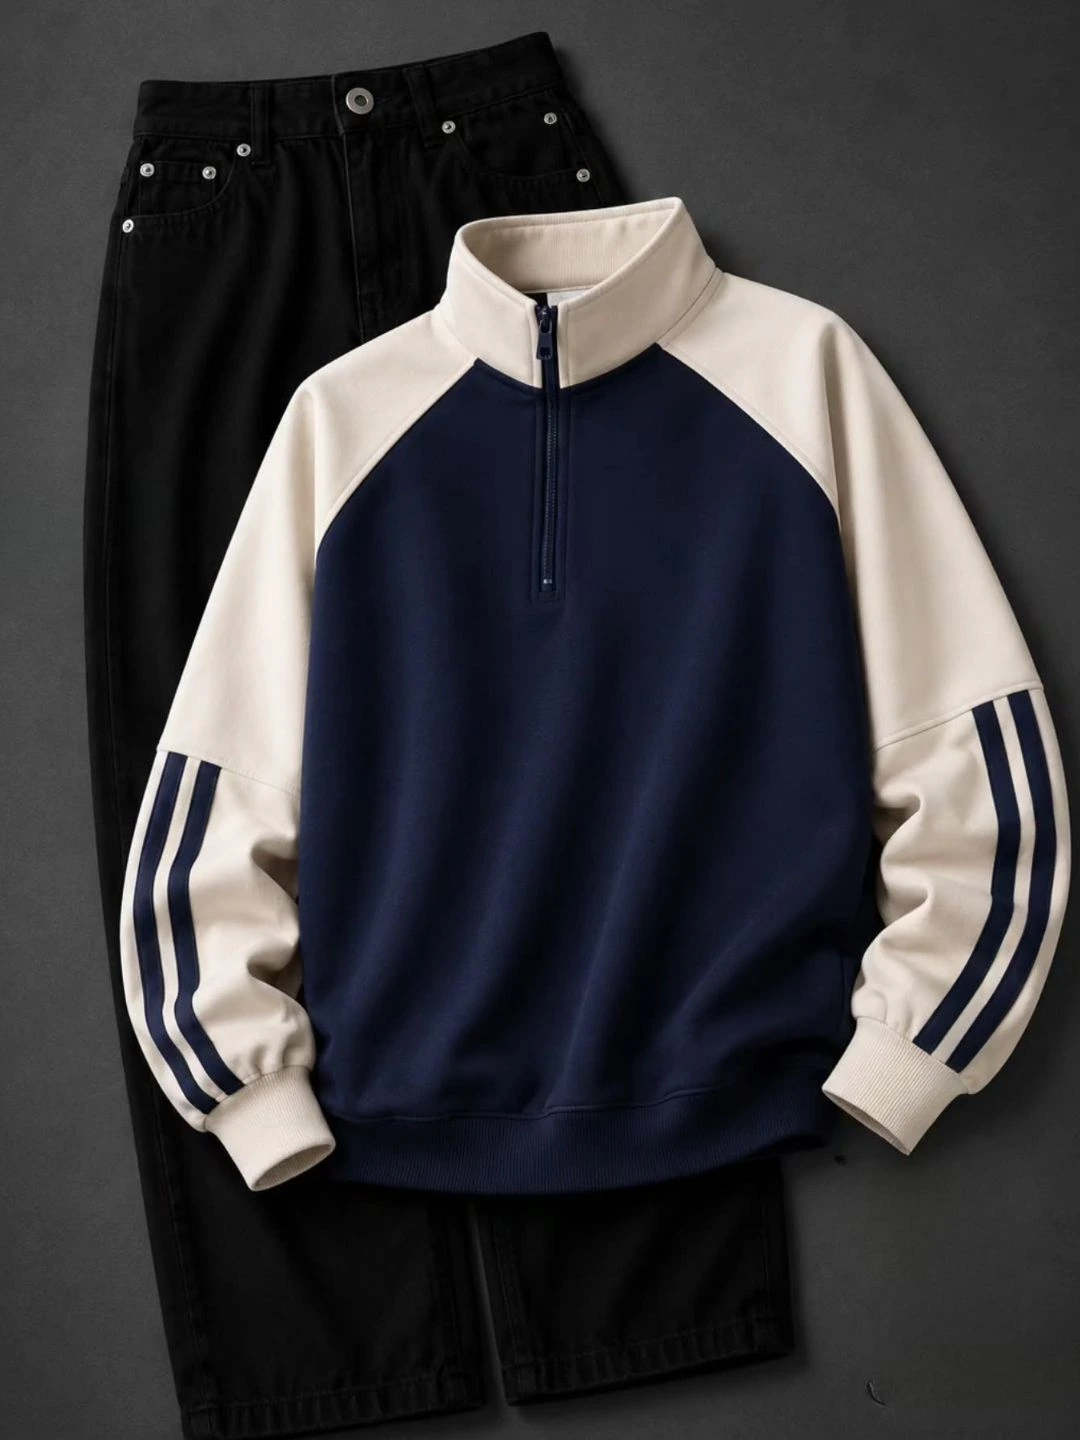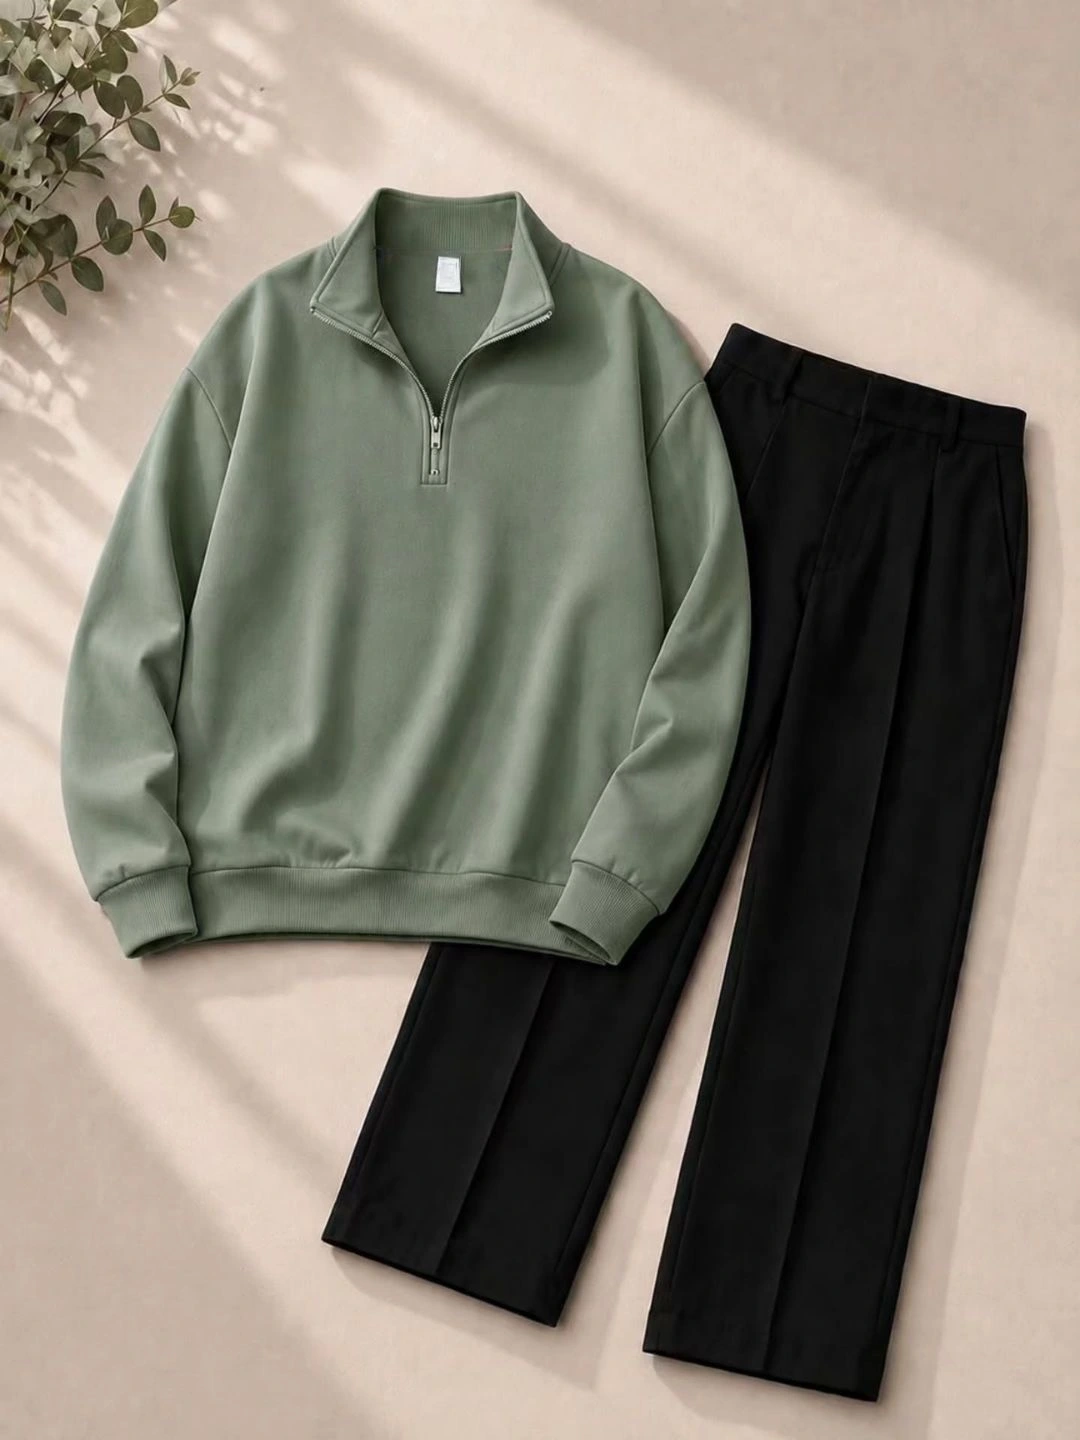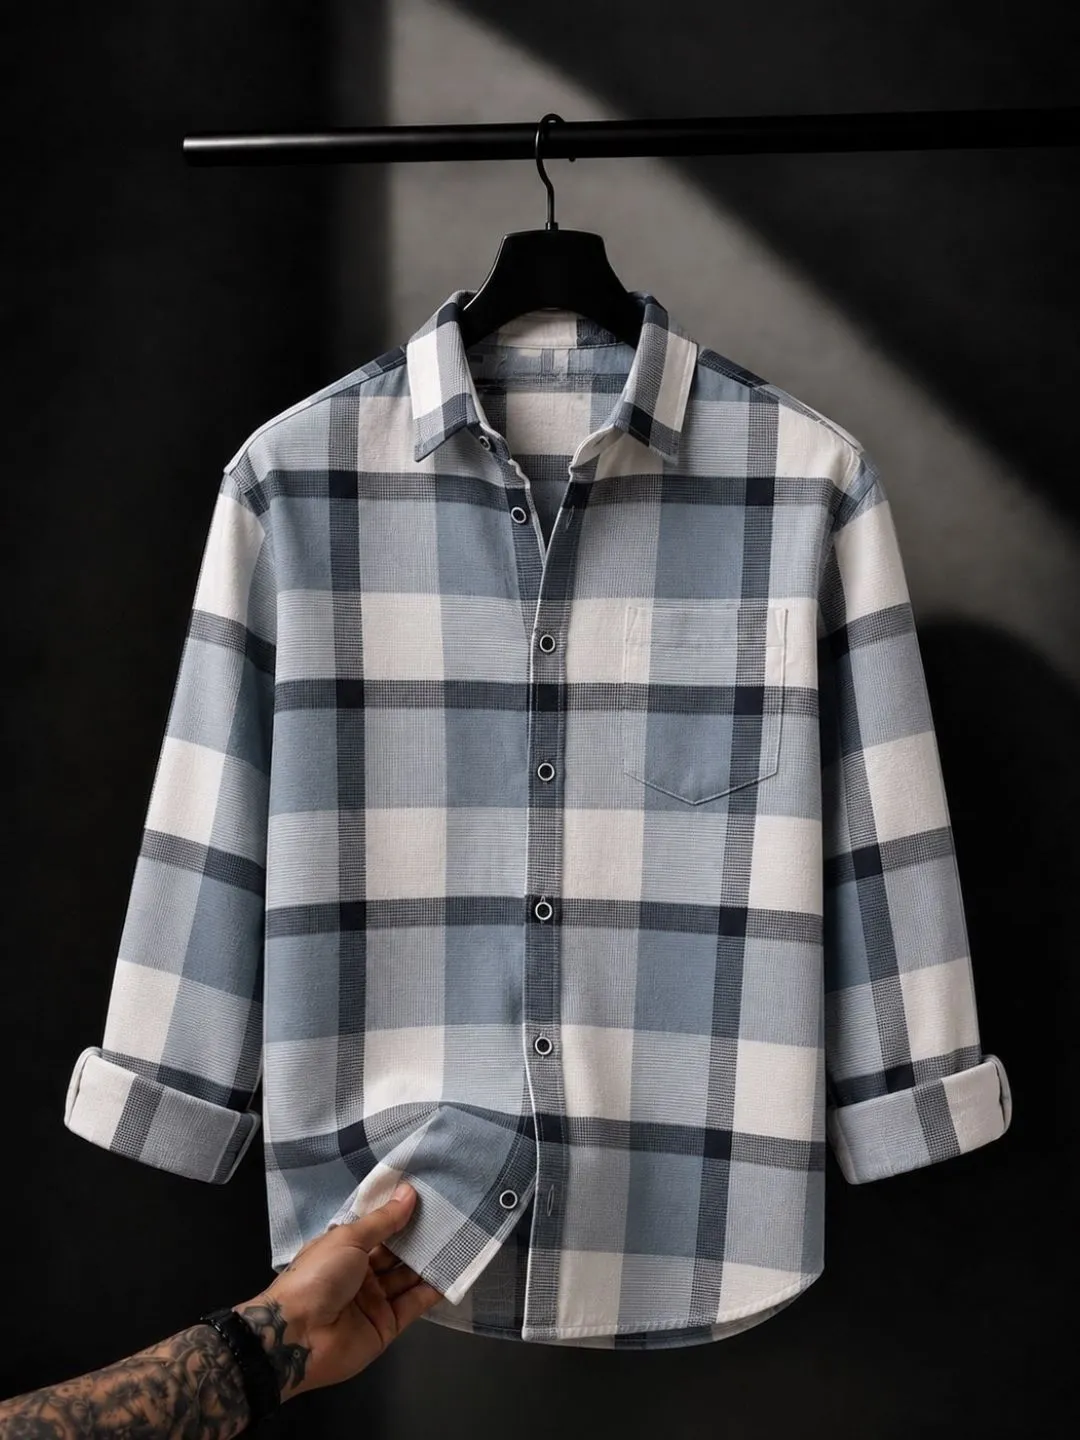
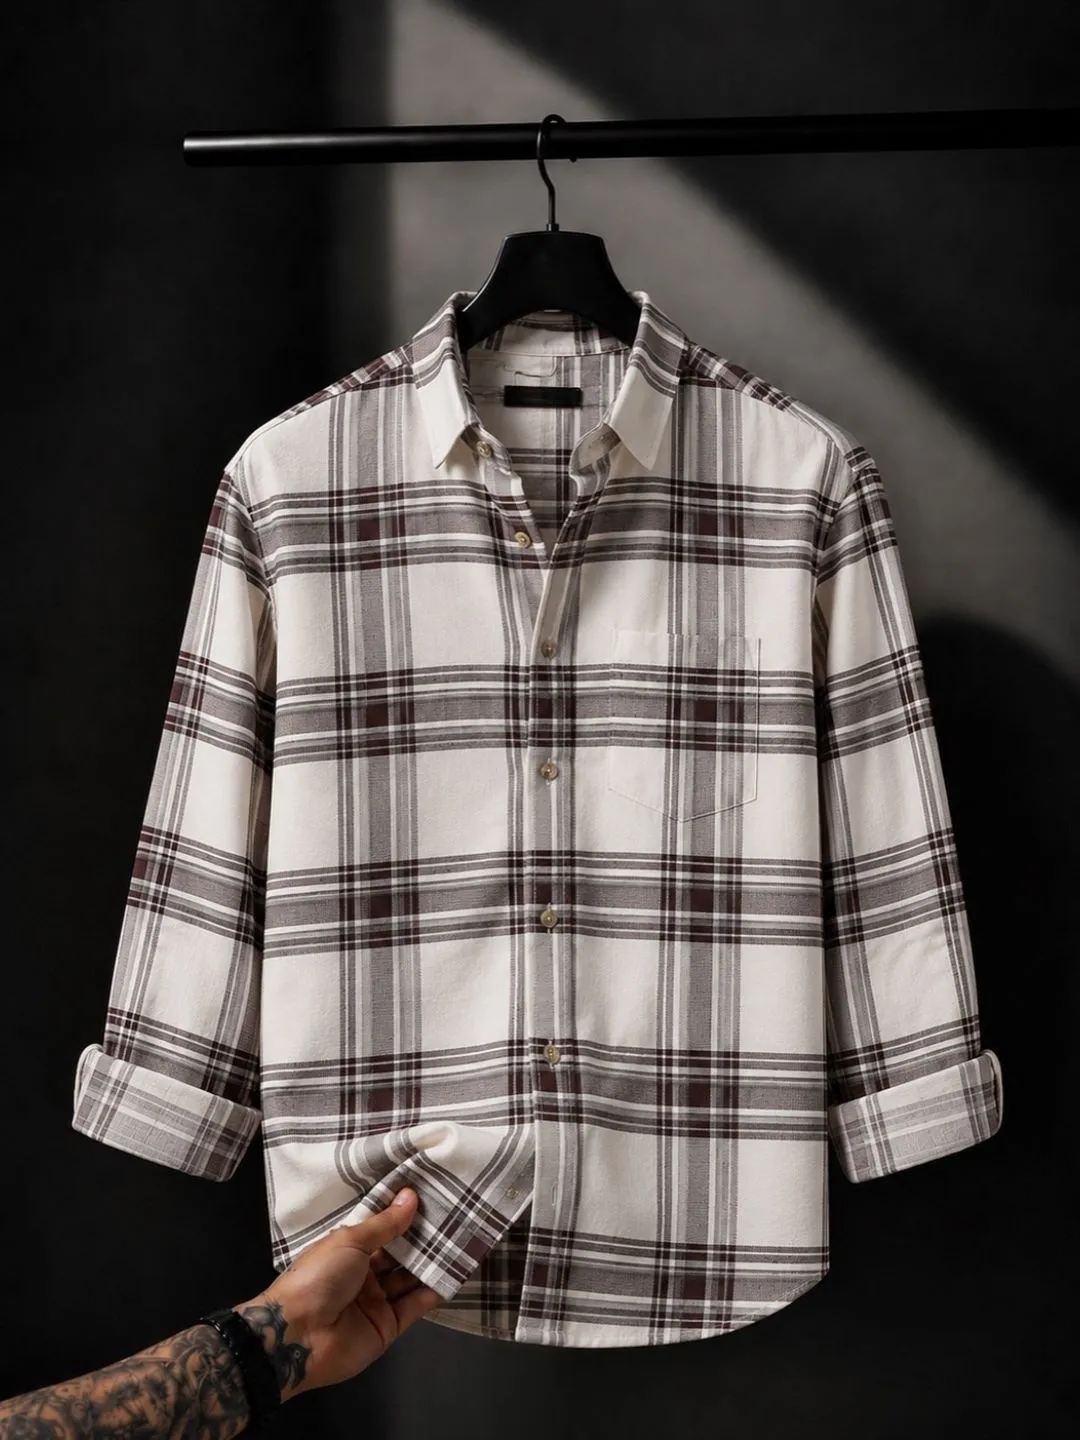
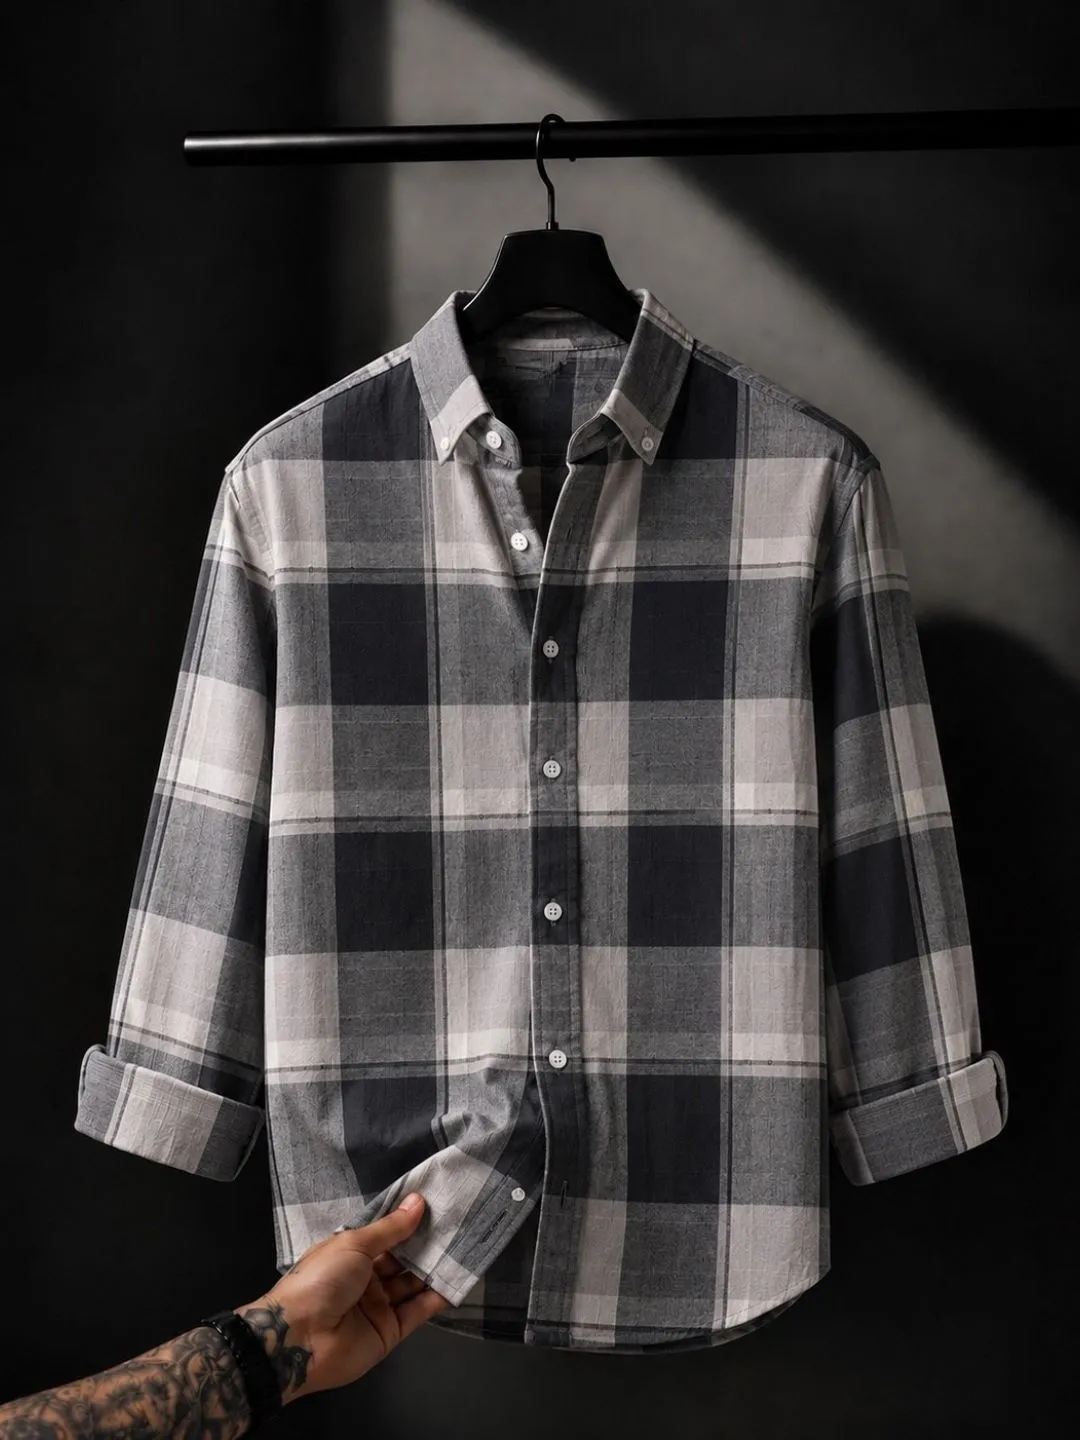
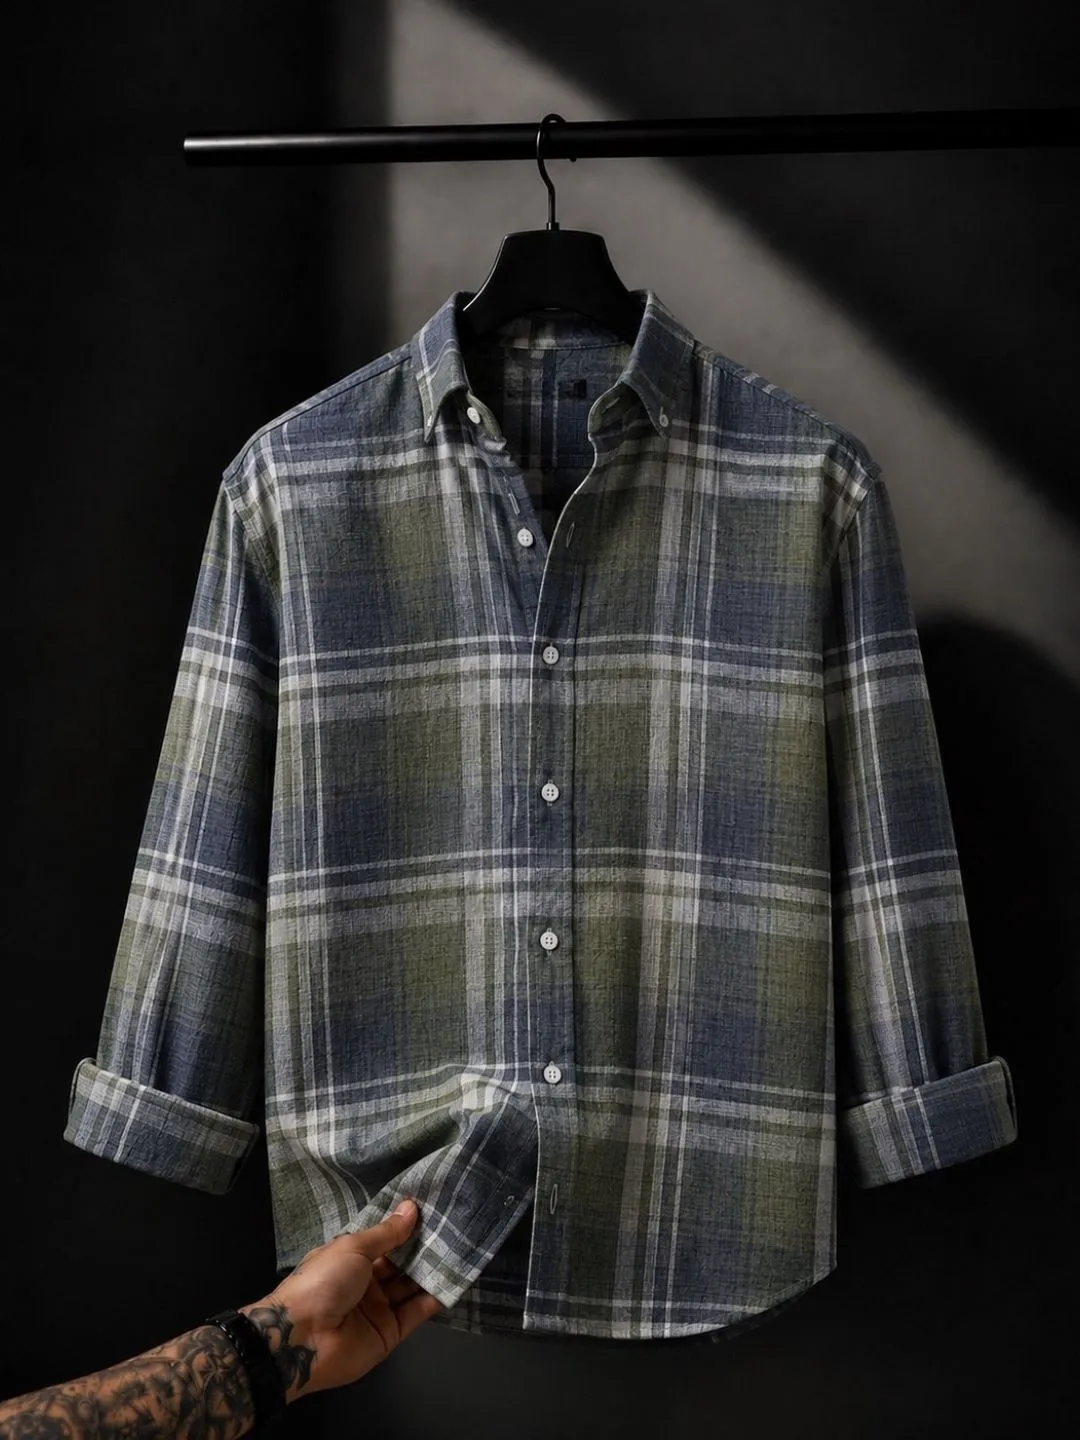
Checked Plaid Long-Sleeve Button-Down Shirt
₹499.00
Sold By
Cotton Culture
3.9
623 Followers
Select Size
Product Description:
Cash on Delivery Available | Limited Stock | Trending Style
Product Details:
Product Type: Button-Down Shirt
Sleeves: Full Sleeves
Fit Type: Modern Tailored Fit
Collar Type: Classic Spread Collar
Fabric: Premium Cotton Blend
Pattern: Classic Plaid Checkered Body with Single Chest Pocket
Style: Casual Smart / Urban Heritage / Modern Minimalist
Occasion: Daily Wear, Travel, Casual Outings, Office Wear
Upgrade your casual wardrobe rotation with this exceptionally stylish and meticulously crafted long-sleeve button-down shirt, featuring a timeless plaid checkered pattern throughout the lightweight body and a convenient single chest pocket. Designed with a structured spread collar and a clean button placket, this versatile garment combines classic heritage styling with contemporary appeal. Crafted from a soft, breathable, and high-quality fabric blend, this everyday shirt guarantees supreme all-day comfort without ever compromising on a sharp, modern silhouette.
There are really two things you're insuring here, and people often only think about one of them. Structure cover protects the physical building itself against fire, storm damage, earthquakes, and similar structural risks. Contents cover protects everything inside — furniture, electronics, jewelry, appliances — against theft, fire, or damage. If you're renting, structure cover isn't your responsibility, but contents cover absolutely should be on your radar, especially if you own decent electronics or gadgets.
One number worth actually calculating properly is the sum insured. A lot of people just guess a round figure, but the right way to do it is based on the reconstruction cost of the house, not the market value, since insurers pay to rebuild the structure, not to cover the land value underneath it. Underinsuring here is a common mistake that only becomes obvious after a claim, when the payout falls way short of what it actually costs to rebuild.
Your no claim bonus is basically a reward for not filing claims, and it can knock a solid chunk off your renewal premium every claim-free year, sometimes stacking up to 50% off over time. The trap a lot of riders fall into is filing a claim for something minor, like a small scratch, and losing that bonus over a repair that would've cost less out of pocket anyway. Before you file any claim, do the math on whether the repair cost is actually higher than what you'd lose in bonus and premium hike.
Buying online has made comparing insurers painfully easy, so there's no real excuse for renewing blindly with whichever company sends the first reminder text. Check the cashless garage network near you, read a few claim settlement reviews, and actually compare IDV, the Insured Declared Value, across insurers, because a lowball IDV means a lowball payout if your bike is ever declared a total loss.